


The August 2026 Texas data center pause is not a headline that belongs only on tech news sites. For contractors building along the I-35 corridor, it is a direct signal to reassess backlog, labor plans, and pursuit strategy before the next quarter’s bid calendar locks in.
Key Takeaways
- Gov. Abbott’s August 3, 2026, directive halting new data center grid interconnections puts roughly 20% of the U.S. data center pipeline-about 49.8 GW-at risk of delay, with Central Texas among the most concentrated exposure zones in the country.
- Contractors with heavy backlog in tech campuses, mission-critical facilities, and industrial construction along the Austin–Round Rock–San Marcos–Waco corridor should stress-test their portfolio concentration, labor plans, and procurement timelines immediately.
- A pause does not equal cancellation. Expect re-sequencing, conditional notices to proceed, redesigns for on-site power, and phased mobilizations rather than a sudden collapse in demand-but cash flow disruptions and bid-date shifts will hit subcontractors first.
- Tighter competition, pricing pressure, and labor redeployment into adjacent sectors like semiconductor manufacturing, healthcare, and public infrastructure are the near-term effects contractors must prepare for.
- This brief closes with concrete next steps: how to reassess sector exposure, adjust pursuit strategy, and plug into ABC Central Texas market-intelligence, workforce development, and training resources.
Why the Texas Data Center Pause Is a Red‑Alert for Central Texas Contractors
On August 3, 2026, Gov. Greg Abbott directed the Public Utility Commission of Texas and the Electric Reliability Council of Texas (ERCOT) to halt approvals for new data center projects seeking grid interconnection until a full audit is complete. BloombergNEF estimates this pause puts about 49.8 GW of planned U.S. data center capacity at risk of delay-roughly 20% of the entire national pipeline-with potential revenue losses reaching $8 billion by Q1 2027 if 60% of that delayed capacity is AI-related.
This is not just a Dallas Fort Worth or a Silicon Valley story. Central Texas data center construction depends on the same ERCOT interconnection process now frozen under the governor’s directive. Data centers in the Austin–San Antonio region face significant scrutiny over their electricity demand on the ERCOT grid, and ERCOT projects 14 percent electricity demand growth by 2026, a surge driven largely by these same facilities. Data center construction spending increased by 28 percent last year, and Texas is the fastest-growing digital infrastructure market in North America. That growth created enormous opportunity for the Texas construction industry-but it also created concentration risk that is now being tested.
Most of the at-risk pipeline consists of next-generation, AI-heavy capacity drawing unprecedented power loads, which directly connects to large electrical, mechanical, and civil scopes that merit shop contractors across central Texas have been staffing and pricing for months. This article functions as a practical market-intelligence brief for company owners, executives, project managers, and field leaders along the I-35 corridor who need to make decisions in the next 3–12 months. It builds on existing regional outlook analysis in the Texas Construction Outlook 2026 and is not a standalone hot-take.
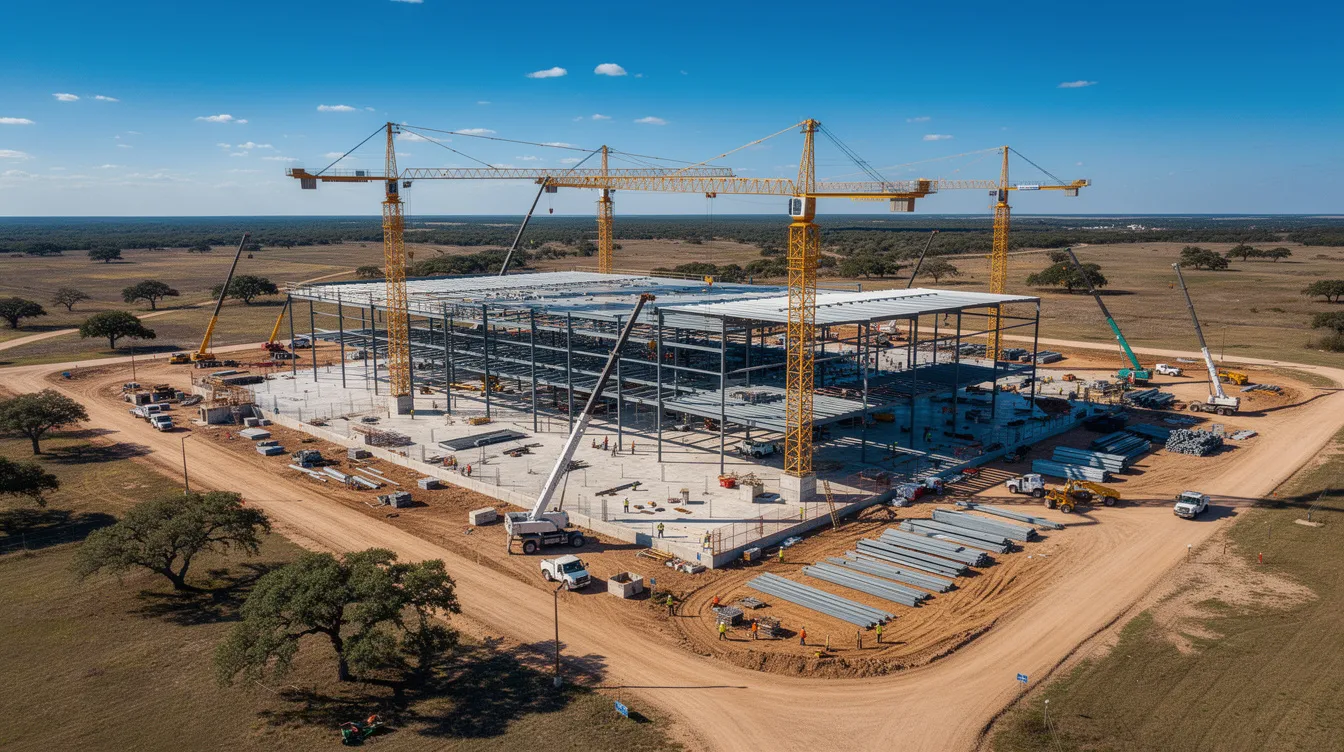
Central Texas Exposure: Where Data Center and Tech Work Concentrate Along I‑35
The Austin–Round Rock–San Marcos metro, plus Waco and surrounding counties, has become one of the nation’s densest clusters for tech campuses, cloud and AI data centers, and power-intensive industrial construction. Central Texas is experiencing a surge in data center construction driven by artificial intelligence and cloud computing, and the region ranks as the second-busiest data center sub-market in Texas. Over 70 data center projects are underway or planned in Central Texas along the Austin–San Antonio corridor, and Central Texas offers large tracts of available land that are attractive for data center campus developments.
Key geographic concentrations include:
- Round Rock and Williamson County: Home to Switch’s “The Rock” campus, Sabey’s facilities, and Skybox’s Old Settlers PUD approved for approximately 75 MW of grid-connected power. These campuses sit near Dell Technologies HQ and draw from the same skilled workforce pool feeding semiconductor manufacturing and advanced fabs near Taylor.
- Hutto and Taylor: Skybox has planned a 600 MW campus in Hutto, and nearby Taylor hosts large semiconductor investments that compete for the same specialized trades-electricians, pipefitters, and HVAC technicians.
- San Marcos and Hays County: The Francis Harris Lane project proposed roughly 380 MW across five buildings on 200 acres, though community objections to data centers include concerns over noise, light pollution, and water usage, and local municipalities are implementing zoning bans or moratoriums on data center developments due to resource concerns.
- Temple, Waco, and McLennan County: Spillover industrial corridors with growing ERCOT interconnection requests. Fewer named megaprojects are public, but load-request clustering is visible in county-level data.
Supporting infrastructure-substations, transmission upgrades, chilled water plants, high-capacity duct banks, and fiber infrastructure-ties data center construction to broader civil and industrial construction work. Cooling has become a major community and regulatory issue in central Texas due to rising water consumption, and electricity and water availability are critical factors influencing data center development across the region.
Texas has a business-friendly taxation and regulatory environment that has been a primary engine for attracting investment. Energy prices in Texas are six times lower than in California; the state has the highest number of Fortune 500 company headquarters in the U.S., and Texas offers a sales tax exemption for data centers over 100,000 square feet, provided they invest at least $200 million to qualify for tax incentives. That regulatory environment is why Texas leads in digital infrastructure-but it is also why the pause hits so close to home.
The specialty trades most exposed are electrical work, low-voltage systems, HVAC, pipefitting, plumbing, sheet metal, concrete, and site/civil contractors that have leaned heavily into mission-critical and tech-campus scopes. These firms have benefitted from rapid growth, but now carry concentration risk if too much backlog is tied to data centers and a small number of technology companies.
What a “Pause” Actually Means on the Ground for Data Center Construction
A pause rarely means instant cancellation across the board. In practice, it typically looks like re-sequencing, extended preconstruction, or conditional notices to proceed while owners and developers wait for regulatory clarity. AI workloads require intense liquid cooling and massive power density, shifting traditional designs for data centers-and those design shifts add time even without a regulatory hold.
Here is what contractors should expect to see:
- ERCOT interconnection studies delayed: Projects requiring 75 MW or more of grid-connected power fall under the Large Load Interconnection process and Batch Zero review. Study timelines stretch from months to potentially quarters. Developers increasingly utilize on-site or behind-the-meter power generation to bypass traditional grid delays, but those redesigns carry their own cost and schedule impacts.
- Phasing changes: Owners may push later buildings or fit-out packages while advancing civil site work and shell construction. This splits mobilization and creates gaps between scope releases.
- Owner-driven slowdowns: Capital discipline tightens when interconnection timelines are uncertain. Bid dates slide by quarters. RFIs and submittals pile up without full funding clarity.
- Redesigns for water supply and power: New facilities must demonstrate high water efficiency and implement noise-reduction technology under evolving compliance standards. Water-efficient designs and planning are becoming competitive advantages for data center developments. These design changes ripple through mechanical, plumbing, and controls scopes.
- True cancellations: When power, water supply, or community opposition cannot be resolved-as happened with zoning rejections in san marcos-projects may be relocated or shelved entirely.
Each scenario hits subcontractor cash flow directly. Trades that ramp early-civil, concrete, site grading-face mobilize-then-pause cycles. Trades that depend on long-lead buys-transformers, switchgear, chillers, generators, UPS systems-face non-cancelable orders, storage costs, and price exposure. Texas regulators are enforcing strict disclosures regarding power usage for new data center approvals, adding another layer of documentation before projects can proceed.
Earlier ABC coverage providing critical insights for data center electrical contractors offers a more detailed look at electrical-trade exposure and should be referenced for continuity.
Backlog Concentration and Schedule Risk: How Vulnerable Is Your Central Texas Portfolio?
Every executive running construction projects in central Texas should treat the 2026 data center pause as a prompt to examine backlog composition by sector, owner, and geography-not just total months of work. The private market for large data centers has been the growth engine, but that engine is now idling while ERCOT clears its queue of roughly 445 GW in large load interconnection requests.
Practical diagnostic steps:
- Calculate the percentage of current revenue tied to data center projects, tech campuses, and mission-critical work.
- Identify how much of that backlog depends on ERCOT-constrained power approvals or utility substation upgrades in Williamson County, Hays County, or McLennan County.
- Map your exposure to single owners or developers-if one hyperscale client pauses two campuses simultaneously, what happens to your Q1 2027 labor plan?
- Look at schedule stacking: identify quarters where multiple data center or industrial construction projects in central Texas are scheduled to peak manpower at the same time. Any slip or pause becomes exponentially more disruptive when projects overlap.
These diagnostics connect directly to broader risk-management themes covered in a Central Texas playbook, positioning this data center episode as a live test of principles around contract terms, contingencies, and schedule cushions. Encourage HR, safety, and field leadership to join the review so that labor allocation, training, and safety plans adjust in step with backlog changes-not after a project goes on ice.
Labor Redeployment, Wage Pressure, and Trade Availability if Data Center Starts Slow
Even a modest slowdown in large data centers can send hundreds of electricians, pipefitters, HVAC techs, and equipment operators back into the central texas talent pool at once. The construction industry is already strained: 92% of texas construction firms struggle to find skilled workers, and the construction unemployment rate in Texas was around 3% in late 2025-meaning available workers were already scarce before the boom peaked. Texas needs 349,000 new construction workers by 2026, and Texas will need tens of thousands more electricians by 2027 regardless of how the data center pipeline resolves.
Short-term effects if starts slow:
- Competition for institutional, public, and nonresidential construction work intensifies as more general contractors and specialized trades chase fewer large industrial construction jobs.
- Bid margins compress. Experienced foremen who had been earning up to $35 per hour plus overtime on data center scopes shift to healthcare, higher-ed, or municipal infrastructure projects along I-35 where rates are lower.
- Dallas-Fort Worth led the nation in industrial permits in late 2025, meaning contractors may pursue out-of-region work in North Texas or the Houston area to keep teams together, or even chase energy projects in the Permian Basin.
- Wage pressure moves in both directions: owners may expect discounts as backlog loosens, while contractors still face rising costs from inflation, extreme heat productivity drag, and the need to retain skilled tradespeople in a tight labor market. The labor shortage does not disappear because one sector pauses.
Contractors competing to win work across sectors need an AI-ready workforce that can move between mission-critical, industrial, and infrastructure scopes. Cross-training and flexible skills matter more than over-specialization in a single project type. Workers in construction trades certificate programs earn $50,000 more over their careers than peers without those credentials-a fact that underscores the value of investing in workforce development even during market turbulence.
Material Costs, Long‑Lead Items, and Procurement in a Volatile Data Center Market
Data centers are among the most material-intensive construction projects in the Texas market, with heavy dependence on long-lead electrical and mechanical equipment already stressed by global demand. Supply chain disruptions are a major challenge for Texas contractors, and Texas construction faces rising material costs due to inflation-a combination that becomes especially dangerous when large, power-heavy projects pause midway through procurement cycles.
Procurement teams should ask these questions when a data center or industrial project in central Texas slips:
- Which equipment orders (transformers, switchgear, generators, chillers) are cancelable or deferrable? What are the restocking fees and storage costs?
- Where does warehousing capacity exist locally, and who bears the cost of stored materials under current contracts?
- How do price-protection clauses interact with delays-especially if orders span across tariff change dates? The July 24, 2026, tariff shift has already introduced significant cost volatility in imported mechanical and electrical components, as covered in guidance on the 2026 tariff shift.
- Are escalation clauses, force majeure language, and suspension provisions reviewed with counsel to clarify liability for redesign-driven changes?
President Donald Trump’s tariff policies and shifting trade regulations add another variable. Orders placed months ago at pre-tariff prices may not be extendable at the same cost if project timelines slip. Communicate early with suppliers and fabricators in central Texas to maintain relationships, explore alternate uses for standard components, and avoid last-minute cancellations that damage trust-those vendor relationships will matter enormously when new projects restart.
Contract Language, Suspension Rights, and Utility Coordination: Protecting Margin Before the Pause Hits
Contract terms are one of the few levers contractors can pull before a pause or audit turns into lost revenue or idle crews. The regulatory environment around texas data centers is evolving quickly, and contracts drafted six months ago may not reflect current ERCOT requirements or state-level audit conditions.
Provisions that matter on central Texas data center construction and industrial construction projects:
- Suspension and restart rights: Define compensation during pauses, including standby costs, demobilization, and remobilization fees.
- Termination for convenience: Clarify what constitutes convenience versus cause, especially when regulatory audits or interconnection studies create indefinite holds.
- Change-in-law clauses: Link financial adjustments explicitly to ERCOT rule changes, PUCT directives, or state legislative shifts affecting data center approvals.
- Phased completion definitions: On multi-building campuses, define substantial completion for each phase so partial occupancies and shell-only turnovers are handled fairly.
Tighten coordination requirements with utilities and grid planners so that general contractors and major subs are not committing to manpower peaks before interconnection approvals are credible. Preconstruction agreements or limited notices to proceed can compensate contractors for design-assist, budget support, and early procurement without fully loading field labor before power approvals are in hand.
Work closely with risk managers and insurance advisors, leveraging patterns from a Central Texas playbook to align contractual risk with realistic project and utility timelines. Austin continues to grow as a hub for infrastructure projects and significant investments in the construction industry, but that growth does not eliminate the need for disciplined contract management.
Adjacent Sectors That Can Absorb Central Texas Labor and Equipment
A data center slowdown does not mean central Texas construction demand disappears. Demand often rotates into other sectors along the I-35 corridor, and construction businesses that diversify pursuit strategies early will maintain revenue continuity while others scramble.
Concrete adjacent opportunities:
- Semiconductor manufacturing and advanced industrial campuses around Taylor and north of Austin, which need similarly heavy MEP, cleanroom, and high-capacity electrical distribution scopes. Many companies are adding jobs in this sector.
- Transportation and water/wastewater infrastructure between Austin, San Marcos, and Waco-projects that draw on civil, mechanical, and controls trades.
- Higher-education and healthcare expansions at Texas State, Baylor, and UT Austin, requiring complex HVAC, plumbing, and electrical work with high power density.
- Public safety and municipal facilities needing heavy MEP scopes-fire stations, police facilities, city buildings that demand backup power and climate change resilience features.
- Renewables, solar power, and grid modernization: Transmission and distribution upgrades, battery storage, and microgrids that align with the oil and gas industry transition and broader energy infrastructure needs.
Firms can map transferable capabilities-high-capacity electrical distribution, chilled water systems, complex controls-from data center projects directly into these adjacent markets. Business development teams should revisit pursuit lists and relationships with public owners, school districts, and institutional clients, anticipating that more contractors will pivot into these spaces if tech demand cools. Merit shop contractors in central Texas have an advantage in open, competitive procurements where performance, safety, and a skilled workforce matter as much as price. The overall vacancy rate in San Antonio is at a record low of 1.8%, signaling that commercial and industrial demand extends beyond data centers across the broader Texas market.
Census data and economic growth indicators confirm that central texas remains one of the fastest-growing regions in many other states’ comparison sets. The question is not whether demand exists-it is whether contractors position themselves to capture it across sectors.
What Central Texas Contractors Should Do in the Next 3–12 Months
This section is a practical checklist for company leaders responding to the 2026 Texas data center pause signal. These are not theoretical recommendations-they are the steps that protect margin, retain crews, and maintain competitive positioning.
- Stress-test backlog exposure: Quantify your percentage of revenue tied to data centers and tech owners. If it exceeds 40%, you have concentration risk that demands immediate diversification planning.
- Revisit labor plans and cross-training: Ensure crews can move between data center, industrial, and public work. Apprenticeship programs in electrical, HVAC, pipefitting, and concrete build the flexible skill sets that insulate firms from single-sector volatility.
- Tighten preconstruction and contract language: Add power and utility contingencies to every new bid. Do not commit field labor before interconnection approvals are documented.
- Update pricing strategies: Reflect both potential competition from displaced contractors and ongoing input-cost volatility from tariffs, inflation, and demand shifts across the construction industry.
- Integrate market intelligence into monthly operations reviews: Track ERCOT queue updates, permit activity, and bid volume alongside financial performance. The Texas Construction Outlook 2026 and related resources provide a framework.
- Use re-sequencing periods productively: Push OSHA training, heat-illness prevention, and upskilling rather than allowing idle time to erode culture or safety performance. Texas invested $850 million in workforce training programs-take advantage of what is available.
- Align estimating, operations, and procurement: Ensure all three teams understand how to handle clauses, allowances, and contingencies on new central Texas data center and industrial construction bids submitted while ERCOT policies are still evolving.
- Monitor adjacent-sector pipelines: Semiconductor, healthcare, water/wastewater, and infrastructure projects along the I-35 corridor represent real, near-term opportunities for firms with transferable capabilities.
How ABC Central Texas Can Help Contractors Navigate Data Center Volatility
ABC Central Texas serves as a hub for market intelligence, workforce development, and advocacy for merit shop contractors across Greater Austin and the I-35 corridor. In a market where Texas data shifts demand patterns quarterly, having access to a vast network of industry peers and resources is not optional-it is operational infrastructure.
- Market-intelligence resources: Regular economic and policy briefings that build on the Texas Construction Outlook 2026 and related market-intelligence content, helping leaders track demand across sectors.
- Workforce and training: Registered apprenticeship programs in Electrical, HVAC, Pipefitting, Carpentry, Concrete, Plumbing, and Sheet Metal-plus safety programs and ConstructionU offerings-keep crews productive during re-sequencing. Electrical apprenticeship enrollment in San Antonio grew 18% from 2023 to 2025, showing that the pipeline is expanding but needs sustained investment. ABC South Texas offers apprenticeship programs to address workforce shortages in parallel.
- Advocacy and policy engagement: Monitoring ERCOT-related legislation and regulatory shifts that affect central Texas data center construction and industrial construction projects, with direct engagement at the Texas Capitol.
The contractors who engage now-strengthening the skilled trades pipeline for the AI era and aligning workforce, safety, and pursuit strategies with the changing data center landscape-will be the ones positioned to capture demand regardless of which sector delivers it. Connect with ABC Central Texas to turn this pause into a planning advantage.
Frequently Asked Questions
These FAQs address practical concerns not fully covered in the main brief and will help central Texas contractors translate trends into day-to-day decisions.
How quickly could paused Texas data center projects along the I‑35 corridor restart?
Timelines will vary significantly. Some projects may restart within a few quarters after ERCOT clears interconnection studies or owners finalize on-site generation plans, while others could be re-scoped or relocated if power, water, or community issues cannot be resolved within city limits. Most Central Texas contractors should plan for staggered restarts rather than a single “all clear” date, and build flexibility into staffing, equipment, and procurement plans through at least late 2027.
Which Central Texas trades are most exposed if data center work slows?
Electrical, low-voltage, mechanical and HVAC, pipefitting, sheet metal, and concrete contractors with heavy data center or mission-critical backlog are most immediately affected, especially around Austin, Round Rock, and San Marcos. Many of these skills are transferable to semiconductor plants, hospitals, higher-ed labs, water and wastewater plants, and other power-intensive infrastructure projects across central Texas.
What indicators should Central Texas firms watch to gauge whether the pause is easing or tightening?
Watch ERCOT queue updates, utility substation and transmission project announcements, major tech-company capital-expenditure guidance, and local permit and zoning hearings for large industrial and data center sites in Williamson County, Hays County, and McLennan County. Combine these external signals with internal metrics like bid volume, hit rate, and changes in subcontractor pricing to build a clearer view of where the Texas market is heading.
How can smaller subcontractors in Central Texas avoid over‑reliance on a single data center client?
Diversify by building relationships with multiple general contractors and owners across sectors-industrial, public infrastructure, higher education, and healthcare-rather than chasing only the largest hyperscale campuses. Invest in safety, quality systems, and workforce training so the firm is prequalified for a wider range of complex Central Texas construction projects, reducing exposure to any one customer or project type.
What is a practical first step for a Central Texas contractor reading this brief?
Schedule a focused leadership meeting within the next 30 days to review backlog concentration, active data center pursuits, and workforce plans across Austin, the I-35 corridor, and nearby markets. Follow that review with outreach to ABC Central Texas for updated market-intelligence resources, apprenticeship and safety training options, and opportunities to engage in advocacy around data center and industrial construction policy that directly affects economic growth in the region.


