


Private nonresidential construction spending is contracting almost everywhere you look-except one category. Data center construction in Central Texas is experiencing rapid growth driven by artificial intelligence, and it is pulling labor, equipment, and scheduling capacity away from nearly every other commercial sector. For contractors in Greater Austin, along the I-35 corridor, through Round Rock, San Marcos, and Waco, this is both the clearest growth signal and the sharpest operational risk in the market right now.
According to Construction Executive, private nonresidential spending fell 2.1% year-over-year in April 2026, yet data centers remain one of the few categories exhibiting significant momentum. Nearly 3,000 data center projects are planned nationwide, and Texas is absorbing a disproportionate share of that pipeline.
Here is what that means for the firms that build, wire, cool, and commission these facilities in Central Texas.
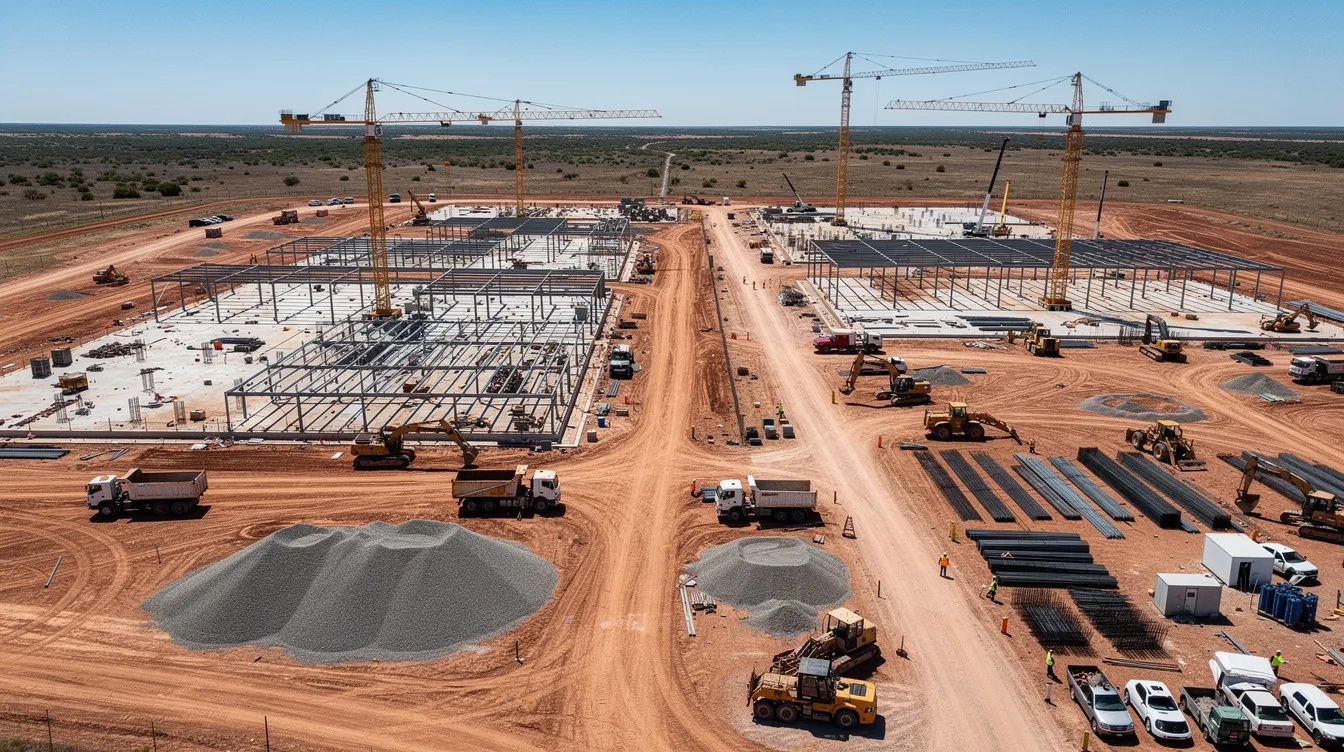
Executive Brief: Central Texas Data Center Construction Market Implications
Data center spending is outpacing every other nonresidential category for a straightforward reason: technology companies need compute capacity faster than the industry can deliver it. Average planned data centers require five times more power than existing ones, and the facilities going vertical today are far more complex than anything the market built five years ago.
In Central Texas, that pressure is acute. Austin’s under-construction data center capacity totaled 463.5 MW in H1 2024, more than double its existing inventory at the time. The region’s data center pipeline is approximately 96% preleased-meaning demand is running well ahead of supply.
The takeaway for Central Texas contractors is binary: this is real, funded work with strong backlog potential, but only for firms that can staff it, schedule it, and deliver it safely. The opportunity and the risk arrive together.
Why Central Texas Feels Data Centers First
Several forces are concentrating data center demand near Austin before it lands anywhere else in the state.
The Texas grid faces constraints that impact data center interconnections. ERCOT manages over 54,100 miles of transmission lines, and the Electric Reliability Council has received more than 438,000 MW of large-load interconnection requests-roughly 89% from data centers. That queue is creating a bottleneck that shapes where projects can actually connect and build.
Austin Energy alone has more than 500 MW in pending large-load requests. Data centers are demanding massive daily water consumption for cooling systems, with some proposed Central Texas facilities estimating 3.5 to 5 million gallons per day. Data centers could account for 3% to 9% of Texas’ water use by 2040, a figure that is forcing regulators and communities to evaluate every proposal through a resource lens.
Recent regulations in Texas require data centers to conduct audits on power and water usage. Governor Abbott’s June 2026 directive mandates that data center operators in Texas may be required to pay for their own power infrastructure upgrades, rather than shifting those costs to residential ratepayers. Residential consumers currently pay more for electricity than industrial ones, and the state is moving to prevent that gap from widening further. Texas has also dedicated $20 billion for water projects over 20 years, but competition for that supply is intensifying.
Demand Hubs: Austin, Round Rock, San Marcos, Waco, San Antonio
Central Texas along the I-35 corridor is a major hub for new data centers. At least 56 projects are planned or proposed in the region, concentrated in suburban and unincorporated areas near urban centers.
Round Rock is a fast-growth node. Switch operates a campus exceeding 1.5 million square feet. Sabey Data Centers completed its first building in late 2024, with an 84 MW campus and a second 54 MW building optimized for liquid cooling now in progress. Skybox Old Settlers has been capped at 75 MW with closed-loop cooling requirements. Texas has 10 new data centers under construction statewide, one the size of Central Park, and Round Rock is absorbing a measurable share of that activity.
San Marcos illustrates the friction. Local opposition to data center construction is increasing due to resource strain concerns, and at least one major project was rejected over water use and community impact. Community relations are increasingly influencing data center permitting and project viability across the corridor.
San Antonio is emerging as a secondary hub south of Austin, with data center developers evaluating sites that offer proximity to power generation and fiber infrastructure. Waco and communities north of Austin are also seeing early-stage interest from data center providers scouting location options outside congested metro cores.
Water conservation is becoming critical in data center design due to severe droughts, especially in the Hill Country and Edwards Aquifer region. Contractors working on these projects should expect closed-loop cooling mandates, landscape buffer requirements, and noise attenuation standards as baseline conditions.
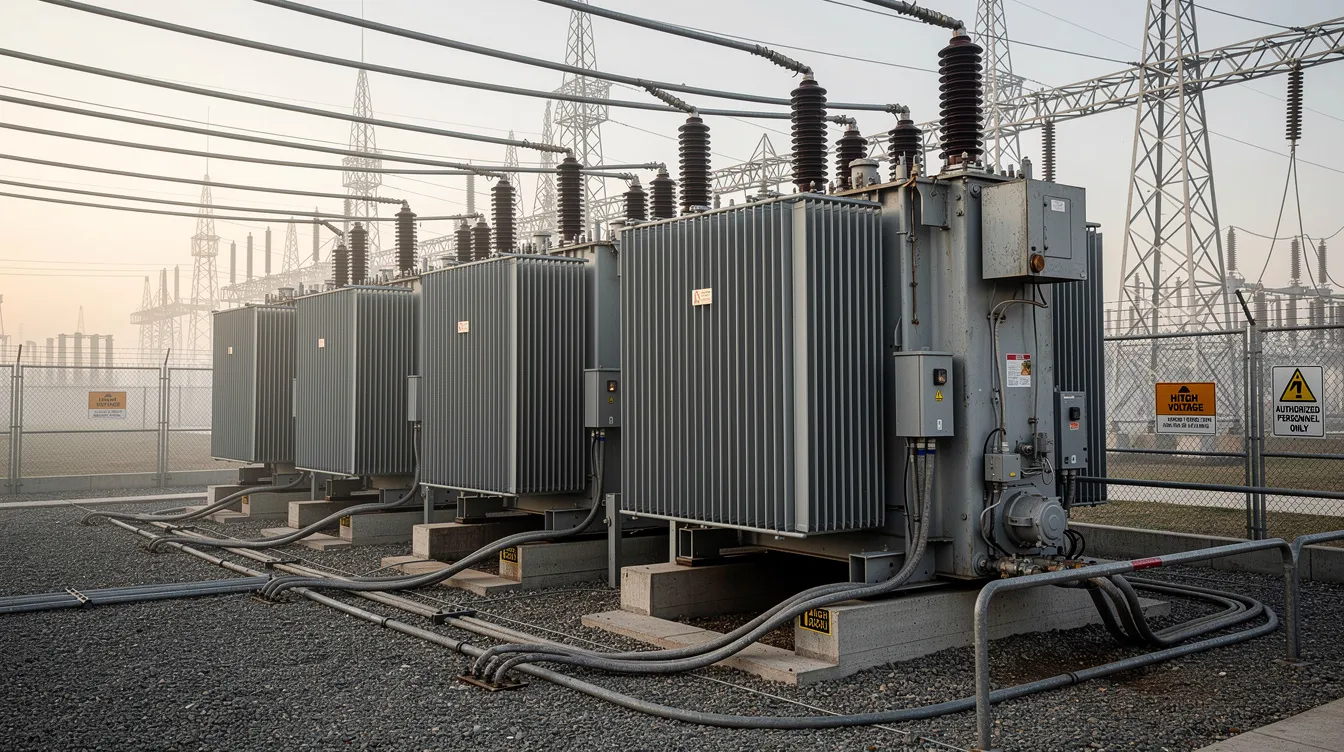
Statewide Comparison: Dallas-Fort Worth and Houston Area Context
Central Texas is not the only market feeling this wave, but the competitive dynamics differ by region.
Dallas-Fort Worth’s data center inventory increased by 4.5% in H1 2024, and the Dallas-Fort Worth metroplex leads the state with approximately 86 planned projects. North Texas has deeper existing infrastructure and more mature campuses, which gives Dallas contractors a head start on certain project types.
The Houston area faces different constraints. Flood risk, utility overlay complexity, and the availability of large parcels with strong grid and water supply make Houston less favorable for the largest new builds. Houston’s energy companies and industrial base create competition for electrical labor that further tightens the craft pipeline.
What makes Central Texas uniquely attractive to data center developers is a combination of factors:
- Texas energy prices are six times lower than California’s, making the state a magnet for attracting investment in compute-intensive facilities
- Texas has the greenest energy grid in the U.S., with significant solar and wind generation capacity
- Texas offers sales tax exemptions for qualifying data centers
- Proximity to Austin’s technology talent and research institutions
- Available land along the I-35 corridor south of Austin, outside congested city limits
These advantages explain why central Texas data center construction is growing faster than the region’s existing contractor base can absorb.
Data Center Trades Under Immediate Pressure
Not all trades feel this demand equally. The hierarchy of pressure looks roughly like this:
| Trade | Share of Data Center Capex | Key Drivers |
|---|---|---|
| Electrical | 45–70% | High/medium voltage, UPS, switchgear, PDUs, generators, redundancy |
| HVAC / Mechanical | 15–25% | Liquid cooling, closed-loop systems, precision environmental control |
| Concrete / Civil | 10–15% | Heavy foundations, transformer pads, floodplain mitigation |
| Commissioning / Controls | 5–10% | 2N redundancy validation, power testing, environmental controls |
AI workloads are pushing data centers towards ultra-high rack densities and complex cooling systems. Facilities in Round Rock are being built to support racks at 250 kW each, requiring under-floor liquid cooling and hybrid mechanical systems that demand specialized pipefitting and plumbing skills.
Data centers may need up to 100 megawatts of power each, and average new facilities require five times the power capacity of older ones. That scale makes electrical scope the dominant cost center and the hardest trade to staff.
How Data Center Spending Reshapes Backlog, Scheduling, and Margins
Contractors actively working on data center projects report average backlogs of 11.6 months, compared to 8.6 months for firms without this work. That gap is both an advantage and a warning.
Shorter bid cycles are compressing preconstruction timelines. Developers want speed, and contractors that cannot produce qualified estimates quickly lose bids.
Equipment lead times for transformers, switchgear, UPS systems, generators, and cooling equipment have lengthened. Projects over 75 MW now require full interconnection studies under SB 6, which can take six months or more. Developers are implementing behind-the-meter power solutions to bypass grid delays, but those add complexity and cost.
Margin risk is real. Steel, copper, and specialty cable costs remain elevated. Schedule compression limits change-order flexibility. Firms that overcommit without verified craft capacity expose themselves to rework, penalties, and degraded safety performance.
Contractors should tighten contract language for delay events tied to utility interconnection, equipment procurement, and regulatory changes. The Batch Zero audit process has effectively paused many projects, and that uncertainty must be priced into proposals.
Labor Constraints and Registered Apprenticeship Responses
Labor-not capital-is the binding constraint on how much central Texas data center construction the region can actually deliver.
Over 60% of data center providers face labor shortages. Construction of new data centers could generate 4.7 million jobs nationally, and average data center projects employ 1,500 to 3,000 workers at peak mobilization. Retirements among tradespeople outpace new apprenticeship entrants, creating a structural deficit that wage increases alone cannot solve.
For Central Texas employers, the response requires three moves:
- Sponsor apprentices now. ABC Central Texas operates DOL-registered apprenticeship programs in Electrical, HVAC, Pipefitting, Concrete, Carpentry, Plumbing, and Sheet Metal. Entry apprentices earn $18–22/hour and progress to $35–45/hour as journeypersons. The training pipeline takes 2–5 years, which means firms must fill slots today to have workers ready for 2028–2030 demand.
- Cross-train journeymen across MEP scopes. Workers who can cover overlapping duties-electrical and controls, mechanical and piping-reduce dependency on single-craft staffing and improve field flexibility during equipment install and commissioning phases.
- Develop foremen and safety leads. Site supervision is the most acute bottleneck on fast-track projects. Managers and experienced craft professionals who can lead crews through complex, high-tolerance work determine whether a project delivers on margin or erodes it.
Safety Risks When Data Center Schedules Compress
When schedules compress, safety exposure rises. The connection is direct:
- Heat illness: Central Texas summer conditions, combined with long shifts on exposed sites, rooftop equipment installs, and concrete work, create severe heat risk. Crews pushed to meet milestone deadlines during July and August face the highest exposure.
- Fall protection: Multi-story data center facilities, cooling towers, roof-mounted generator houses, and elevated switchgear installations require constant fall-protection vigilance. Refresher training before mobilization is not optional.
- Fatigue: Extended overtime, compressed turnover between project phases, and understaffing degrade attention. Fatigued workers make errors that lead to rework and incidents.
Contractors should increase foreman-to-crew supervision ratios on data center jobs. Require heat-illness and fall-protection refreshers before mobilization. Schedule STEP and OSHA training during the planning phase, not after crews are already on site.
Quick Q&A for Central Texas Contractors
Why is data center spending still strong right now? Demand for compute capacity-driven by artificial intelligence, cloud migration, and enterprise workloads-is outpacing supply. Technology companies and data center developers are racing to deliver preleased capacity, and that spending is largely insulated from the broader nonresidential slowdown.
Why does Central Texas see outsized demand? Low energy costs (six times lower than California), available land along the I-35 corridor, proximity to Austin’s technology and research ecosystem, solar and wind power generation resources, and favorable tax policy make the region a preferred location. President Donald Trump’s administration has also signaled continued federal support for domestic data infrastructure, further accelerating the pipeline across the country and in Texas specifically.
Which trades must expand capacity first? Electrical contractors face the most immediate pressure, followed by HVAC/mechanical, pipefitting, and concrete. Commissioning and controls specialists are also in short supply.
How do compressed schedules increase safety risk? Tighter timelines push crews into overtime, reduce rest between shifts, and limit supervision coverage. Heat, fatigue, and fall hazards all occur more frequently when the schedule drives the pace rather than the safety plan.
How do apprenticeship programs mitigate labor shortages? Registered apprenticeship builds a pipeline of trained, credentialed craft workers with industry-specific skills. Firms that sponsor apprentices see lower turnover, reduced rework, and stronger safety records-advantages that compound on large, technically demanding projects.
Action Checklist: What Central Texas Contractors Must Do Now
- Inventory current trade capacity and forecast gaps by trade, especially electrical, HVAC, and pipefitting
- Sponsor apprentices through ABC Central Texas programs before the next training cycle fills
- Prequalify critical subcontractors with verified bonding, technical capability, and staffing resources
- Tighten procurement plans with long-lead contingencies for transformers, switchgear, generators, and cooling equipment
- Schedule STEP and OSHA refresher training before peak summer mobilization
- Join industry committees for real-time market intelligence, advocacy, and networking with firms operating in this sector
- Evaluate contract language to protect margins against utility delays, regulatory changes, and materials escalation
Next Steps, Links, and Central Texas Resources
The data center market is not slowing down. The contractors who gain share in this cycle will be the ones who staffed, trained, and planned before the next wave hits. Central Texas data center construction rewards preparation-not reaction.
ABC Central Texas provides apprenticeship intake, safety training, and industry networking built for this moment. Contact the chapter to develop your workforce pipeline, schedule safety readiness training, or connect with the market intelligence resources that help you determine where to deploy your next crew.


